When a Small Mishap Doesn’t Have to Wreck Your Rates
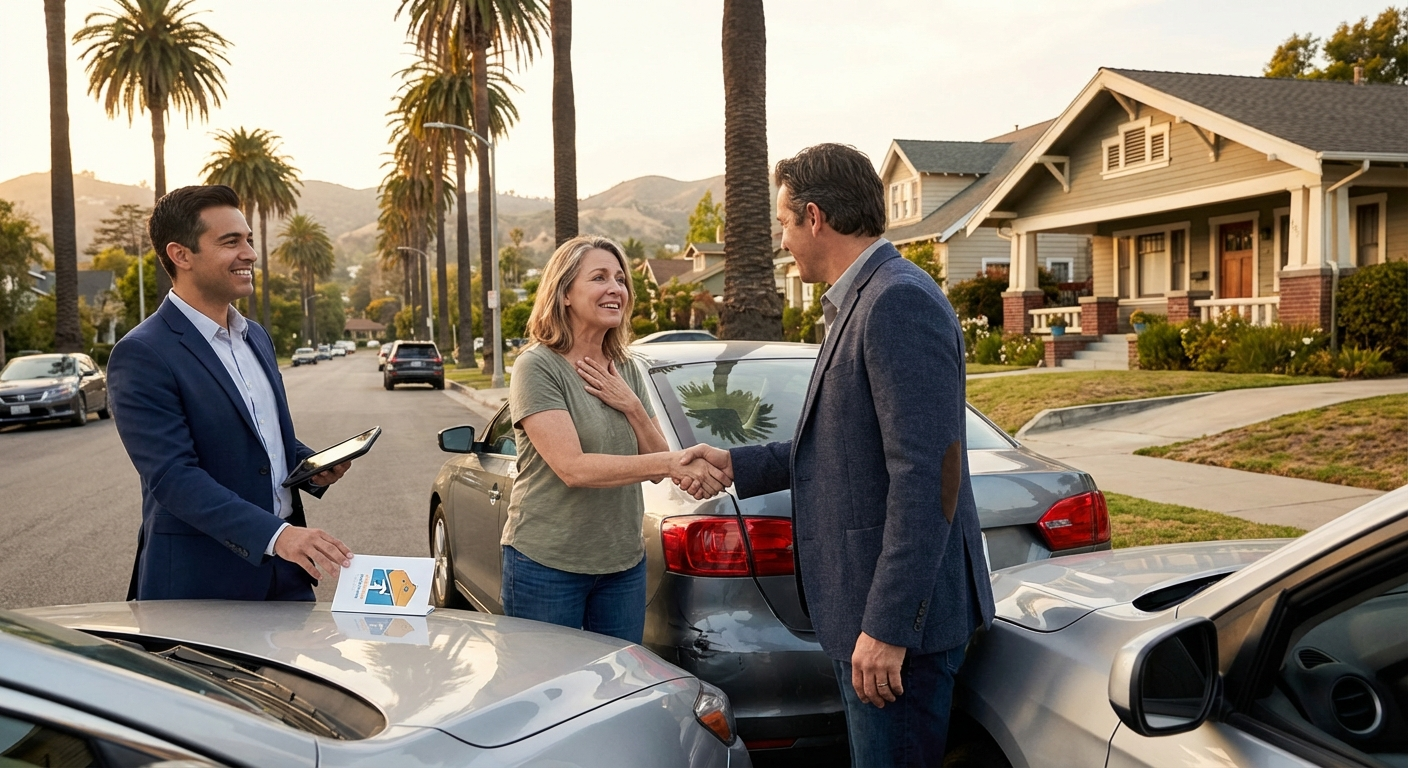
Maria was running late, as usual. It was a Tuesday morning, 7:45 AM, and she was doing her best to get her two kids dropped off at school in Pasadena before fighting the traffic on the 101 into the Valley for work. She’d just pulled out of the school lot, easing her minivan into the flow of cars, when it happened. A quick glance in the rearview, a moment of distraction, and *thump*. Nothing major, just a little tap on the bumper of the car in front of her. No injuries, thankfully. Just a dented fender on the other car and a minor scratch on Maria’s.
She exchanged information, apologized profusely, and then the worry started to creep in. Her insurance premiums were already high — living in Southern California, who’s aren’t? She’d had a clean driving record for years, maybe even a decade. But one little bump? Could this single accident send her rates through the roof? Her mind immediately went to the dreaded rate hike.
This is where something called “accident forgiveness” could have been a real lifeline for Maria. It’s a concept many California drivers hear about, maybe see advertised, but don’t quite understand. Is it real? Does it actually work? And what does it mean for someone driving on our crowded freeways, from San Diego up to Sacramento?
What Accident Forgiveness Really Means
Think of accident forgiveness as a kind of Get Out of Jail Free card for your first at-fault accident. The idea is simple: if you qualify and have this feature on your policy, your insurance company won’t raise your rates solely because of that one accident. It’s a buffer, a little bit of grace for an honest mistake.
But here’s the thing. It’s not some magical, automatic promise. Most insurers don’t just hand it out to everyone. There are rules. You’ve got to earn it, in a way. Usually, it’s an add-on to your policy, something you pay a little extra for. Sometimes it’s a perk for long-term, loyal customers with a spotless driving history.
For Maria, with her decade of accident-free driving, she might have been a prime candidate. If she’d had accident forgiveness, that little fender bender wouldn’t trigger the typical premium increase. That’s a big deal when you’re already budgeting for gas, groceries, and housing costs in places like Orange County or the Inland Empire.
The Fine Print: Eligibility and How It Works in California
Okay, so who gets this golden ticket? It varies a lot by insurer. Generally, companies like State Farm, AAA, and Farmers offer some version of accident forgiveness, but their specific criteria can differ wildly.
Typically, you’ll need a clean driving record for a certain number of years. Five years is a common requirement. Some companies might ask for even more, maybe seven or eight years without any at-fault accidents or major violations. You also usually need to have been a customer with that specific insurer for a few years – sometimes three, sometimes five. They want to know you’re a good risk, a proven quantity.
Which brings up something most people miss. Accident forgiveness usually only applies to your *first* at-fault accident. It’s not a lifetime pass for multiple mistakes. You use it once, and then you typically have to “re-earn” it over another few years of clean driving. It’s a one-and-done deal for a while.
In California, the insurance market is unique. Proposition 103, passed back in 1988, gives the state a lot of power over how insurance companies set their rates. This means that while insurers can offer accident forgiveness, the specifics — how much it costs, what the eligibility rules are — still fall under the watchful eye of the California Department of Insurance. This also means there’s less wild west pricing and more regulation compared to some other states. But it doesn’t mean it’s free. You’ll still see a slight bump in your annual premium to add it on, usually. For some, that small extra cost is worth the peace of mind.
Is It Worth the Extra Cost?
This is where opinions diverge. Some drivers swear by accident forgiveness. They see it as a smart investment, especially if they drive a lot, commute through busy areas like the 405 or the 5, or have teenagers just getting behind the wheel. The cost of a minor premium bump for the feature often pales in comparison to the potential rate hike after an at-fault accident. We’re talking hundreds, sometimes even thousands, of dollars saved over a policy term if a rate increase is avoided.
Others might argue it’s an unnecessary expense. If you’re an extremely cautious driver, rarely on the road, or have an older car that wouldn’t incur massive repair costs, maybe you don’t feel the need. But here’s the reality for most Californians: we drive a lot. The odds of a minor fender bender over a decade are, well, pretty good.
Consider Maria again. If her monthly premium was, say, $150, and an at-fault accident without forgiveness bumped it up by 20% to $180, that’s an extra $360 a year. If accident forgiveness cost her an extra $5 a month, or $60 a year, it would have paid for itself after just a few months post-accident.
What About the “Not So Forgiven” Stuff?
It’s important to understand what accident forgiveness *doesn’t* cover.
For starters, it typically only applies to at-fault accidents where you are deemed responsible. If someone else hits you and it’s clearly their fault, your rates shouldn’t go up anyway. That’s what their insurance is for.
Also, things like major moving violations — DUIs, reckless driving charges, multiple speeding tickets — those are usually completely separate. Accident forgiveness won’t protect you from the sky-high premiums that come with those kinds of offenses. Those are serious marks on your record, and insurers will react accordingly. Expect to see your rates jump dramatically in those situations, regardless of any forgiveness perk.
Another point: if you switch insurance companies *after* an accident, your new insurer won’t care if your old company “forgave” you. They’ll look at your driving record, see the accident, and rate you based on that. Accident forgiveness only works with the company that granted it to you. This is a common misunderstanding.
Finding the Right Policy for You
Trying to sort through all the different auto insurance policies and add-ons can feel like navigating the spaghetti bowl of freeways around downtown LA. Every company has its own rules, its own pricing structures, and its own definition of what a “good driver” looks like. That’s why talking to an experienced agent, someone who understands the California market inside and out, can make a big difference.
Someone like Karl Susman, from LA Car Insurance Quotes, CA License #0B75129, has been helping California drivers for years. He’s seen how things change, from the increasing frequency of natural disasters impacting home insurance (like the 2025 LA fires and FAIR Plan adjustments) to the constant shifts in auto premiums. An independent agent like Karl can compare options from multiple carriers – State Farm, AAA, Farmers, and others – to see which ones offer accident forgiveness that truly fits your driving habits and budget. You can reach him and his team at (877) 411-5200.
They can help you understand the nuances, like whether your specific driving history would even qualify you for accident forgiveness, or if another policy feature might be more beneficial for your situation. It’s not just about getting the cheapest rate; it’s about getting the *right* coverage.
Remember Maria and her little fender bender? After the initial panic, she called her agent. Luckily, she *did* have accident forgiveness on her policy, an add-on she’d almost removed a few years back to save a few bucks. That small monthly fee saved her a much larger headache, and kept her rates from climbing right when she needed every penny. It was a good reminder that sometimes, paying a little extra for peace of mind pays off in a big way.
Want to explore your auto insurance options, including accident forgiveness, with an expert?
Get a California auto insurance quote today!
Frequently Asked Questions About California Accident Forgiveness
Does every insurance company in California offer accident forgiveness?
No, not every insurer offers it. It’s a common feature from many of the larger carriers like State Farm, AAA, and Farmers, but it’s an optional benefit. Smaller or specialty insurers might not have it. You’ll need to check with your specific provider or ask an agent like Karl Susman.
How long do I usually have to be a customer to qualify for accident forgiveness?
Most insurers require you to be a policyholder for a certain period, usually three to five years. They want to see a history with them before they extend this perk. You’ll also typically need a clean driving record during that time.
If I use accident forgiveness, does the accident still appear on my driving record?
Yes, the accident will still be on your official driving record with the DMV. Accident forgiveness simply means your current insurer won’t raise your rates *because* of that specific accident. If you switch insurers, the new company will see the accident on your record and could rate you differently.
Is accident forgiveness the same as a disappearing deductible?
No, they are different things. Accident forgiveness prevents your rates from going up after an at-fault accident. A disappearing deductible — sometimes called a diminishing deductible — reduces your deductible amount over time for every year you don’t file a claim. You could even get to a $0 deductible after several years of claim-free driving.
Can I add accident forgiveness to my policy at any time?
Usually, you can add it when you first get your policy or at renewal. Some insurers might let you add it mid-term if you meet all eligibility requirements, but it’s often something you opt into at the start of a policy period.
Ready to see how accident forgiveness could fit into your auto insurance plan?
Click here to get a California auto insurance quote!
This article is for informational purposes only and does not constitute financial advice.